Net-leased Mister Car Wash in Port Charlotte sells for $6 million
Marcus & Millichap brokered the sale of the 2022-built absolute NNN property to an Indiana-based 1031 exchange buyer seeking tax-efficient Florida income.
By The Car Wash News Staff
3 min read
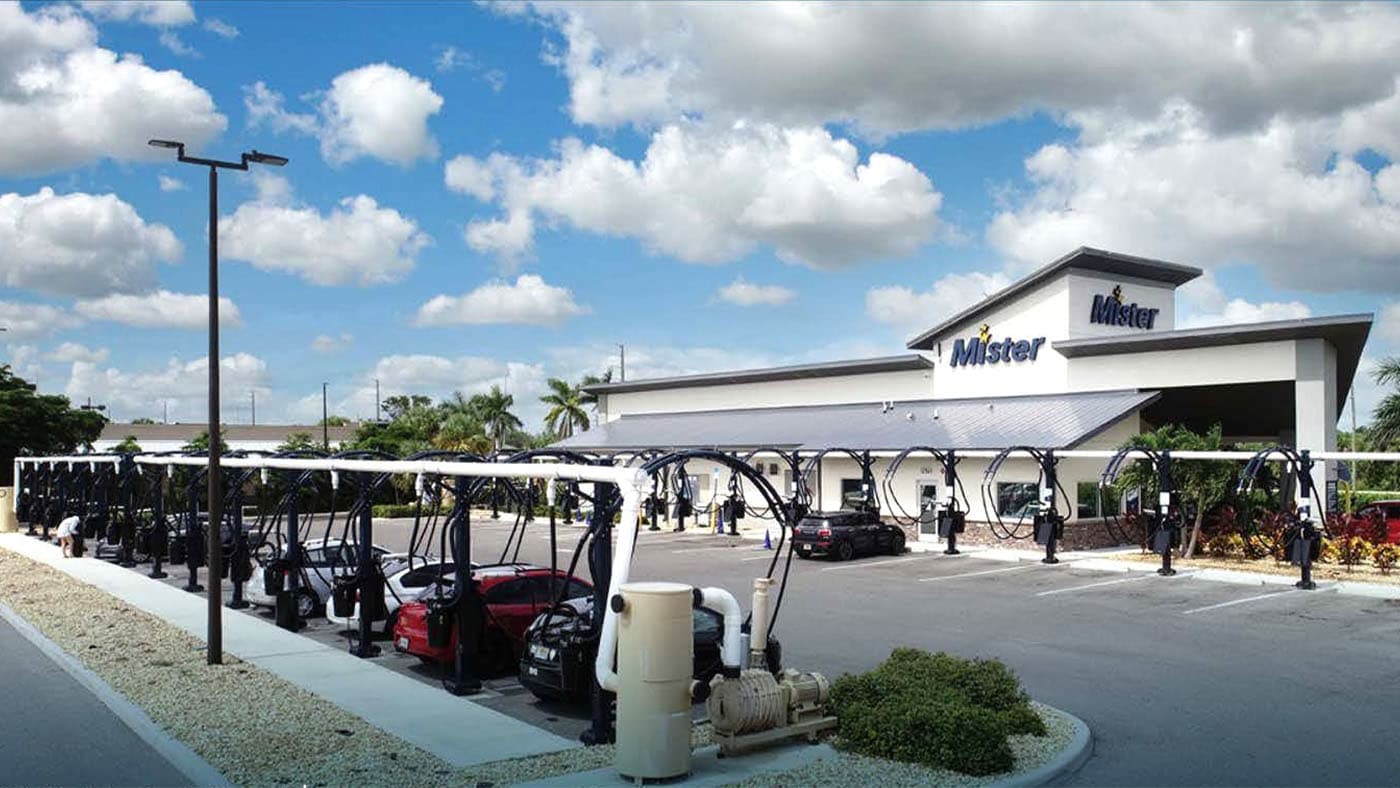
A net-leased Mister Car Wash property in Port Charlotte, Florida, has changed hands for $6,012,000, in a deal that highlights continued investor appetite for car wash real estate backed by corporate-guaranteed leases.
The transaction was arranged by commercial real estate brokerage Marcus & Millichap, according to reporting from Professional Carwashing & Detailing. The site at 12561 S. McCall Rd. was built in 2022 and sits on 1.47 acres. The buyer was described as a private, Indiana-based investor completing a 1031 exchange, who plans to hold the asset long term for cash flow.
Why the property drew interest
The brokerage pointed to a combination of factors that made the offering attractive to net-lease investors. The property carries an absolute triple net (NNN) lease, meaning the tenant is responsible for property expenses, and it provides a long-term income stream guaranteed by the corporate tenant. Senior managing director Dominic Sulo, who works out of the firm's Chicago Oak Brook office, said the deal benefited from the availability of full bonus depreciation.
"Investor demand for tax-efficient net lease investments remains strong," Sulo said, citing high-growth Florida markets where demographic trends support long-term real estate fundamentals. He worked the deal with Ryan Nee, the firm's Florida broker of record, who helped procure the buyer.
The sale reflects a broader pattern in which car wash sites operated by large, credit-worthy brands are increasingly treated as stable commercial real estate investments rather than simply operating businesses. The predictable rent payments, long lease terms, and tenant-covered expenses appeal to passive investors looking for dependable yield.
Why it matters for operators
Transactions like this one offer a window into how the investment community values car wash real estate, and that matters to operators regardless of whether they plan to sell. The pricing on a single net-leased site reflects both the strength of the tenant's credit and the underlying market demographics, two things operators can influence over time.
For independent operators weighing expansion, the sale-leaseback and 1031 exchange activity surrounding car wash properties signals that there is an active pool of capital willing to own the real estate while an operator runs the wash. That dynamic can free up capital for operators who do not want to tie up cash in land and buildings, though it also means committing to a long-term lease with expense obligations.
The emphasis on corporate-guaranteed income is also a reminder of how much tenant strength drives valuation. Smaller operators cannot offer the same balance sheet backing as a national chain, which typically means their real estate trades at higher cap rates and lower per-site prices. Operators considering an eventual exit should recognize that the durability of their lease terms and the quality of their location will shape what investors are willing to pay.
Finally, the role of bonus depreciation in this deal underscores how tax treatment can move car wash real estate. Operators and prospective sellers should factor current depreciation rules into timing decisions, since shifts in tax policy can directly affect buyer demand and achievable pricing.